There Is 45 Billion Dollars of Demand for Climate Resilience and Almost Nothing to Sell Into It
Insurers have been pricing this risk with real money for years, and the money that arrives after a disaster is still structured to rebuild exactly what burned down.
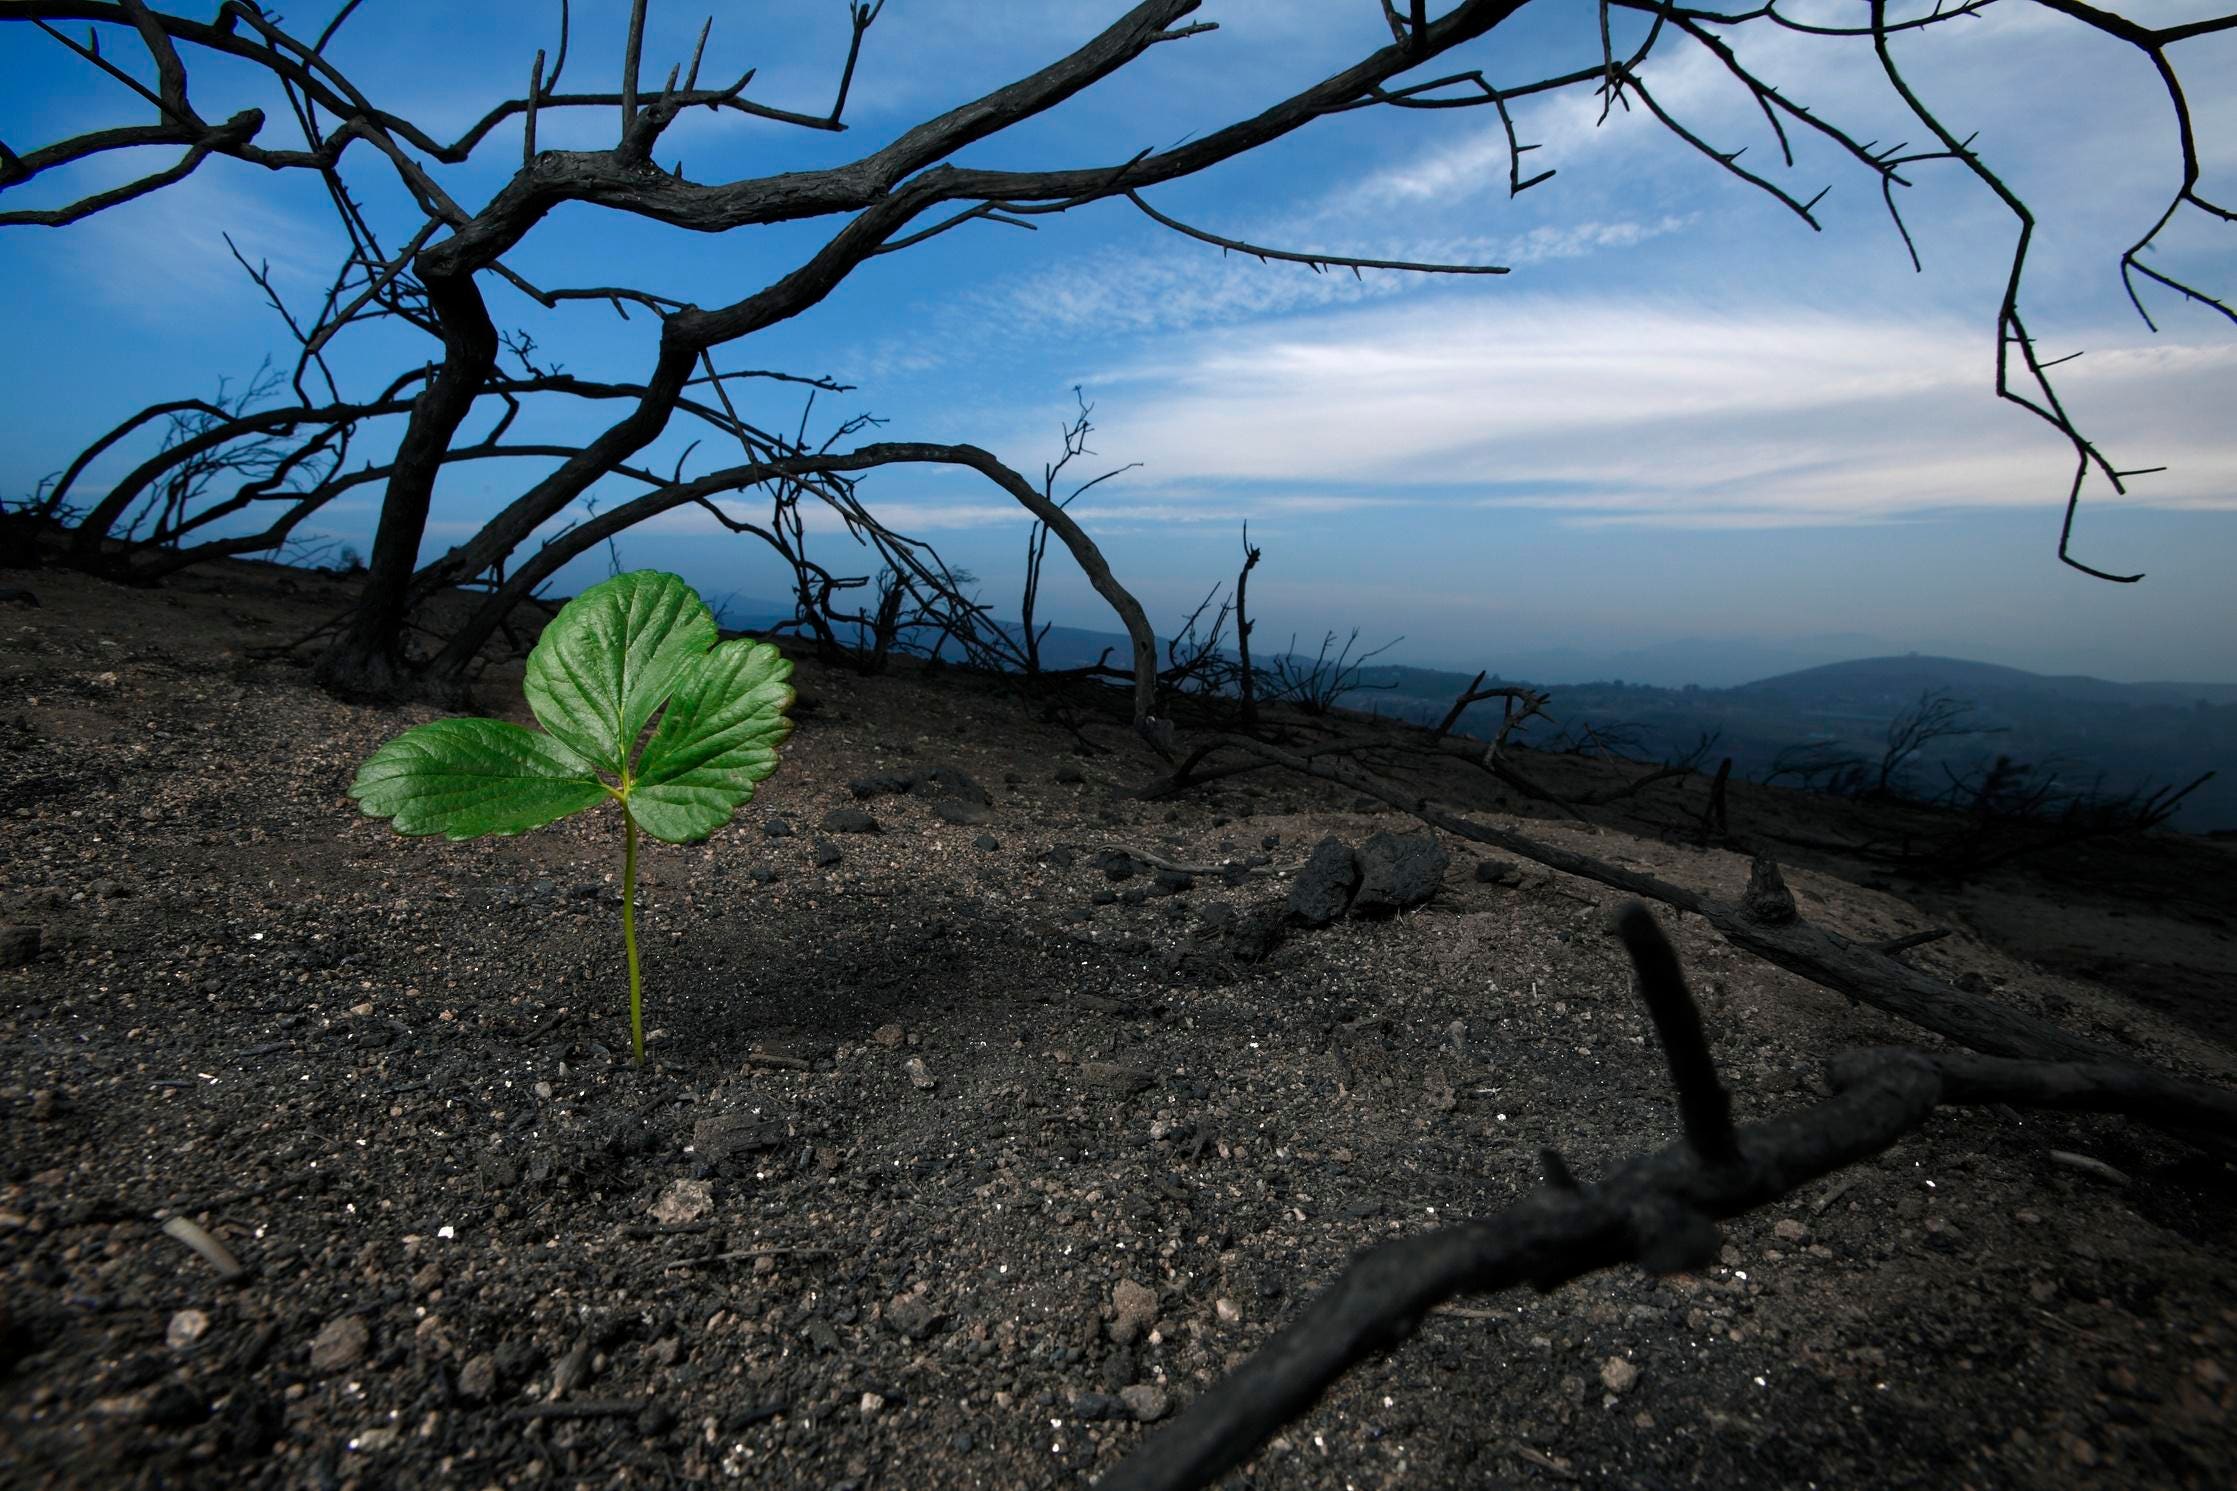
A year after the Palisades and Eaton fires destroyed close to 13,000 homes, Los Angeles had issued roughly one residential rebuild permit for every five homes it lost. That was while the city was permitting at about three times its historical pace.
The insurance money moved considerably faster. Around 40 billion dollars in insured losses was paid out on what became the costliest wildfire event ever recorded, and it went where insurance money is designed to go, which is putting back what was there before.
That is the structural problem, argues Tenzin Seldon, founder and managing partner of Pulse Fund, who has spent two decades around climate capital. Almost none of the money that arrives after a disaster is structured to reduce the cost of the next one.
Four cents in the dollar
The proportions are the part worth sitting with.
By Seldon's calculations, less than four cents of every dollar spent on climate globally goes towards adapting to conditions that are already locked in. The remainder goes to reducing future emissions.
Both matter, and the imbalance is not ideological. Mitigation spent the last decade building companies with customers, contracts and unit economics. Adaptation has not done that work yet, so an institutional investor who wanted to fund resilience would struggle to find anything to actually buy.
The demand is not in doubt
The signal from the insurance market has been unambiguous for years.
A Treasury review of 246 million homeowners policies found nonrenewal rates roughly 80 per cent higher in the ZIP codes most exposed to climate risk. Households in those areas already pay 82 per cent more in premiums than households in the least exposed ones.
Insurers have been underwriting this with their own capital for a long time, which means the market accepted the premise well before anyone was writing essays about it. The gap sits further down the chain: there is a near-total absence of companies whose product reduces the loss rather than repricing it.
The UN Environment Programme puts private capital flowing into adaptation at roughly five billion dollars a year, and estimates realistic near-term potential at ten times that. That leaves about 45 billion dollars of addressable demand with almost nothing built against it.
A gap that size, with demand this visible, is a supply problem
Why the supply is missing
A gap that size in a market with demand this visible usually indicates a supply problem, and in Seldon's experience that almost always means the business models have not been worked out, rather than that customers are absent.
Mitigation went through the same passage, and it was unpleasant. For years climate companies could raise on impact and policy tailwinds. Then the market stopped accepting that, on the entirely reasonable grounds that a product which is not cheaper, faster or better than the incumbent will eventually lose to the incumbent.
A great many companies did not survive that transition. The ones that did are more durable for it, and can sell into any policy environment, which was always the point.
Adaptation has not had that reckoning. Until it does, Seldon does not expect significant private capital to arrive.
Everyone is building the same thing
What capital has gone into adaptation has concentrated in one layer, which Seldon describes as eyes on the sky: the satellites, catastrophe models and analytics that identify where risk sits and how it is moving.
The logic is sound. Insurers and asset owners will pay real money for better information about assets they already hold. ICEYE's 521 million dollar raise this year was the largest climate deal outside energy and transport. Floodbase, a Pulse Fund portfolio company, operates in the same layer.
The trouble is that the category is filling up, and differentiation is getting harder to defend. More than that, there is a ceiling built into the proposition.
Better information about where a fire will burn improves how the loss is priced. It does not change how large the loss is.
That distinction is the whole investment thesis. The 45 billion dollars is waiting for companies that reduce the damage, and what has been funded so far mostly measures it more precisely.
More from Business
Nvidia Is Buying Hugging Face for 12.93 Billion Dollars and Promising Not to Change It
The company that sells the hardware is acquiring the platform where developers choose what to run, and the whole deal rests on a pledge of neutrality.
A Mortgage Holding Company Says the Industry Digitised the Paperwork and Left the Work Alone
Swish Holdings argues that twenty years of lending technology turned documents into PDFs without removing a single step, and it is building a stack…